

What is the best business bank account for a property management company?
Quick answer: For the management company's own operating account, Slash is the best fit. Slash comes with virtual accounts¹ with their own account numbers for each property, office, or reserve, maintenance cards grouped by property with merchant and spending limits, vendor bill pay with approval chains, and QuickBooks, Xero, NetSuite, and Sage Intacct sync, all for $0 or $25 a month per entity. Owner rent and tenant security deposits are different: many states require them in a trust or escrow account, which Slash doesn't offer, so it’s better to keep them at a bank that opens trust accounts your state accepts. Chase fits offices that deposit cash, Mercury fits firms that want free wires on a $0 plan, and Relay and Bluevine fit smaller firms that need a few sub-accounts.
A management company handles two kinds of money. Its own money (fees, payroll, office costs, maintenance parts) can sit in any business account. Meanwhile, money it holds for others (owners' rent, tenants' security deposits, owner reserves) usually has to sit in a trust account under state rules. The best setup splits the two: a trust bank for client funds and an operating account built for controlling spend.
Below, we compared six options property managers ask about most, on monthly fees, how each separates money, trust accounts, and FDIC coverage.
Competitor details checked November 16, 2026, on each provider's own site.
"Not listed" means we couldn't find the feature on the provider's own pages. It’s best to confirm current terms, and confirm that any account holding client funds meets your state's trust-account rules, before you sign on with a provider.
Best picks by type of property management company
- Best for the management company's operating account: Slash. Virtual accounts per property or office, maintenance card groups with merchant limits, bill pay with approvals, and ledger sync, all at a flat price per entity.
- Best for trust and escrow accounts: Enterprise Bank & Trust. A dedicated property management team that helps companies open and properly vest broker trust accounts, plus escrow accounts.
- Best for cash and in-person deposits: Chase. Business Complete Banking includes $5,000 in in-branch cash deposits each statement cycle at no additional charge.
- Best for free wires on a $0 plan: Mercury. $0 ACH and domestic wires on every plan.
- Best for small firms that need a few sub-accounts: Relay or Bluevine. Relay allows 20 checking accounts per business on its $0 and $30 plans; Bluevine offers up to 50 sub-accounts.
Keep trust money and operating money apart
Many states come with specific rules that regulate how a property manager holds other people's money. Oregon’s Real Estate Agency, for example, says a property manager must open at least one clients' trust account, plus a separate one for security deposits held for owners and tenants, at a federally insured bank with at least one physical branch in Oregon. Trust-account bank fees must be paid from your operating account, and keeping your own or your business's money in a clients' trust account counts as commingling.
Other states set their own rules on titling, bank location, interest, and reconciliation. Confirm your state's rules with your real estate licensing agency or attorney before you pick any provider, and keep trust funds where state law requires.
Slash isn't a trust bank. Its eligibility page says Slash accounts are intended for a business's own operating activity, and that Slash can't support accounts used to receive, hold, move, or distribute funds on behalf of customers or other third parties. Rent collected for owners, security deposits, and owner reserves belong in your trust accounts. Slash is for the management company's own money.
Mercury, Relay, and Bluevine don't list trust or escrow accounts on the pages we checked, and Chase doesn't list them on its Business Complete Banking page. Enterprise Bank & Trust does: its property management team says it helps companies open, properly vest, and manage broker trust accounts and verifies that compliance standards are met. It also offers escrow accounts, lockbox services, remote deposit capture, and Positive Pay, and AppFolio lists it as a banking partner. However, Enterprise doesn't publish pricing.
Why Slash fits the management company's operating account
Virtual accounts for each property, office, or reserve
Slash virtual accounts are separate buckets inside one Slash account, each with its own balance, transaction history, and account and routing numbers. Set one up per regional office, per property your in-house team maintains, or for a payroll reserve. Cards can draw from a virtual account, so a property's maintenance spend comes out of that property's bucket.
Virtual accounts are not trust accounts. Their balances belong to the entity that owns the Slash account, so use them for your company's own funds, never owner rent or security deposits.
Maintenance cards grouped by property
Maintenance is where operating costs can leak a bit. Slash issues unlimited virtual cards plus physical cards, and a card group sets rules once for every card at a property or on a crew: a utilization limit on total spending over a period, transaction size limits, and allow or block lists by merchant category, MCC, or merchant. A group for one apartment complex could allow only hardware and building-supply merchants, cap purchases at $1,500, and cap the group at $6,000 a month.
The standard Slash card is a charge card issued by Column N.A. that settles daily from your Slash checking account, so there's no interest or carried balance, and it earns up to 2% cash back on both plans. Receipt and memo policies can require a receipt above an amount you set and text the cardholder a reminder.
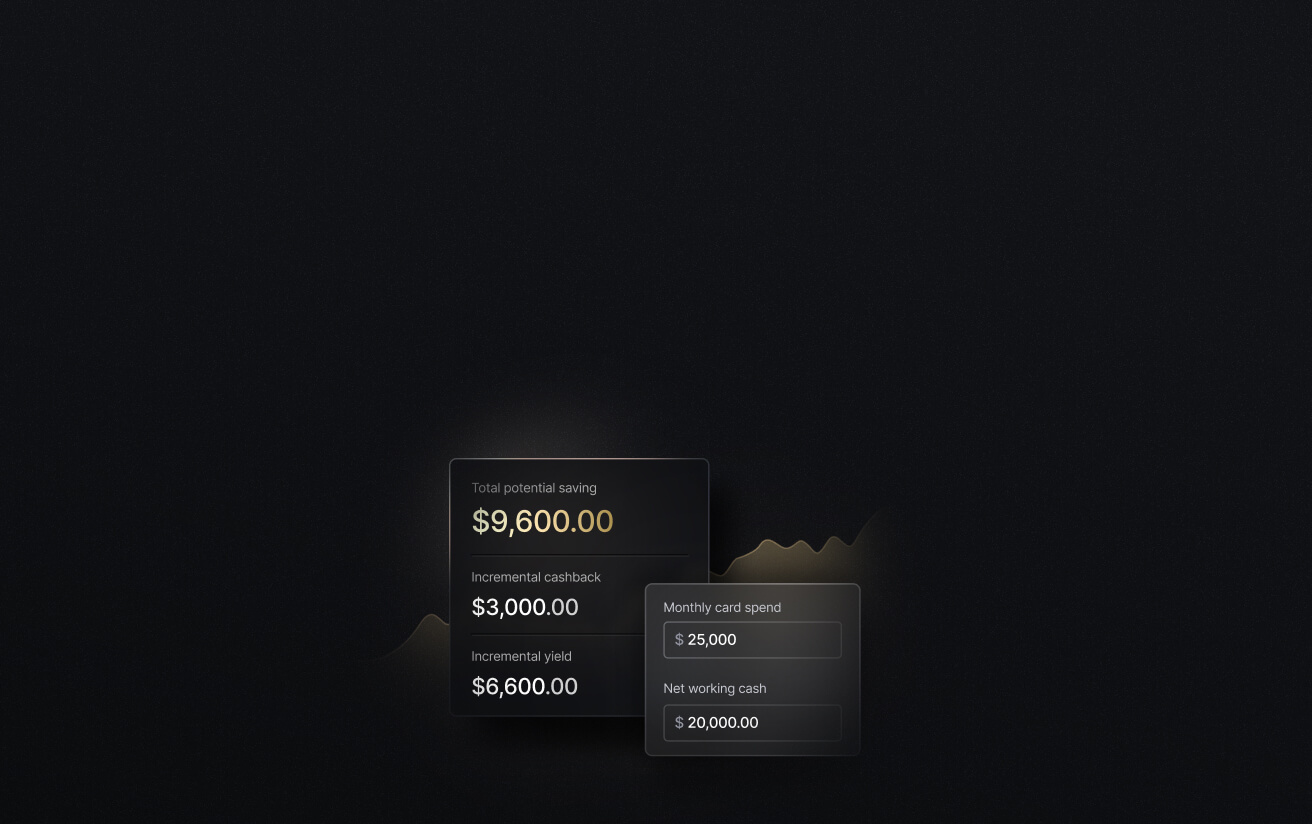
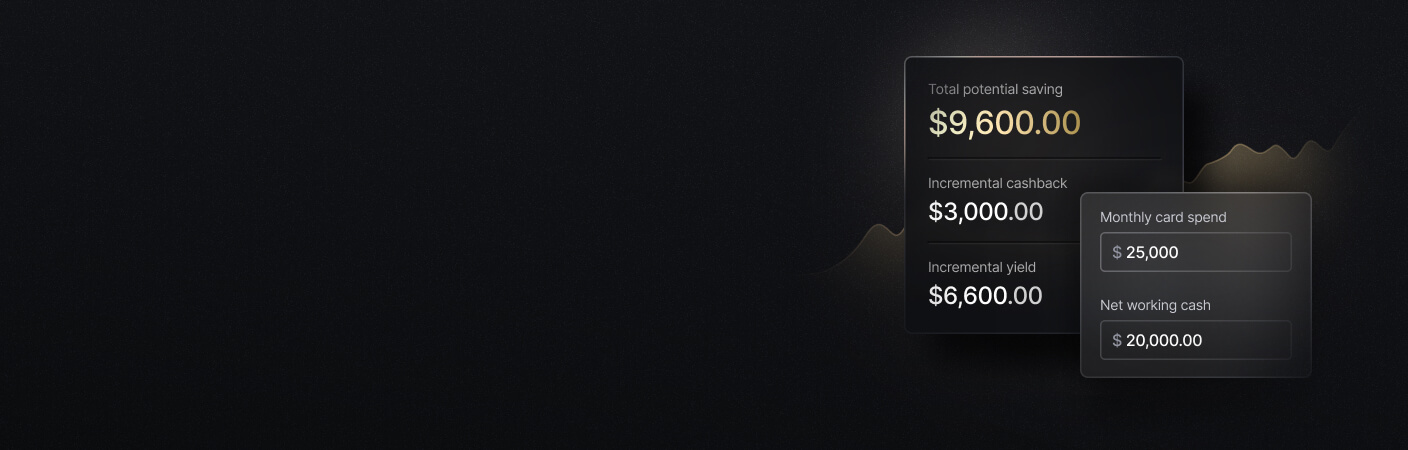
See the ROI behind your spend
Use this calculator to understand impact, then manage and track it all in Slash.
Vendor invoices with approvals
Plumbers, roofers, turnover crews, and landscapers often invoice all month. Slash Bill Pay gives each account an AP inbox for forwarded invoices, reads uploads with OCR, and pays by ACH or wire, now or on a scheduled date. Payment policies send payments that match conditions such as amount and requester through an approval chain with one or more steps, so a $9,000 roof repair waits for the property manager and then a principal. On Pro, same-day ACH and domestic wires are $0, while they cost $1 and $6 respectively on Free.
Accounting sync with property and location tags
Slash connects to QuickBooks Online, Xero, NetSuite, and Sage Intacct on both plans. NetSuite imports classes, departments, locations, customers, and subsidiaries, and Sage Intacct imports those five plus projects. Mapping rules fill in a class, location, or project automatically based on the card, card group, or virtual account behind each transaction, so a property's maintenance spend arrives tagged. You review entries, mark them Ready to Sync, and sync.
Slash syncs with general ledgers, not property management software; its pricing page doesn't list AppFolio, Buildium, or similar systems. Owner and tenant ledgers stay in your property management software and trust bank.
FDIC coverage for operating cash
Slash's banking partner is Column N.A., Member FDIC, and FDIC insurance is available up to $200M through Column N.A. and the IntraFi sweep network, which matters when operating cash builds up between payroll runs. Mercury offers up to $5M, and Relay and Bluevine up to $3M each, against standard coverage of $250,000 per depositor at each insured bank.
Flat pricing per entity, including owners' property LLCs
Slash charges $0 on Free or $25 a month on Pro per entity, with no per-user fees, so adding maintenance techs and leasing agents doesn't change the bill. One login holds unlimited entities, each with its own application and plan, so property LLCs your principals own can bank under the same login. Our guide to business bank accounts for real estate LLCs covers that setup from the investor's side.
What is the best business bank account for a company with multiple entities?
Many management companies also run a maintenance company, a brokerage, or a holding company. Slash puts unlimited entities under one login, each on its own plan, and the Multi-Entity Overview shows each entity's balance, available funds, and spend next to combined totals, with monthly statements for several entities in one download. Access can differ by entity, so a bookkeeper can be an Accountant on one and a Viewer on another.
Relay lets one login hold any number of legally distinct US businesses, and Mercury links several companies to one profile. For a wider comparison, see top fintech platforms for multi-entity banking.
What is the best business card for controlling spend across multiple properties and teams?
The best card lets you set rules once for a whole property or team. Slash card groups do that on both plans: one spending cap across every card at a property, merchant category and merchant rules, and per-transaction limits, with cards drawing from that property's virtual account. Roles and permissions can give a property manager access to specific card groups and virtual accounts only.
Mercury offers custom spend limits and merchant-locked cards on every plan, and its IO card pays 1.5% cash back. Relay includes built-in spend controls on its $0 plan, Bluevine issues up to 50 debit cards with spending limits, and Chase offers Associate Debit Cards on request.
What are the trade-offs?
- No trust accounts on Slash: Owner funds and security deposits need a bank that opens trust accounts your state accepts.
- Cash: Slash, Mercury, Relay, and Bluevine are built around electronic payments. Chase includes $5,000 in in-branch cash deposits per statement cycle at no additional charge.
- Entity type: Slash serves US-registered LLCs, C-Corps, and S-Corps. Sole proprietorships are not eligible.
- Payment fees on free plans: Slash Free charges $1 per same-day ACH and $6 per domestic wire, and Pro removes both. Mercury charges $0 for both on every plan. Bluevine charges up to $10 for same-day ACH and up to $15 for outgoing wires.
- Plan gates at Relay: Multi-step approval rules start on Grow at $30 a month, and fee-free same-day ACH starts on Scale. Its pricing page lists QuickBooks and Xero as its accounting integrations.
- Specialist banks: Enterprise Bank & Trust doesn't publish pricing; expect a sales conversation, not an online signup.
Verdict
Run a property management company on two kinds of accounts: trust accounts for owner funds and security deposits at a bank that meets your state's rules, such as Enterprise Bank & Trust, and an operating account built for controlling the company's own spend.
For that operating account, Slash is our pick: virtual accounts per property or office, maintenance card groups with merchant and spending limits, vendor bill pay with approval chains, and ledger sync with property tags, all at $0 or $25 a month per entity with no per-user fees and FDIC insurance up to $200M through Column N.A. and the IntraFi sweep network. Add Chase if your offices handle cash, choose Mercury for free wires on a $0 plan, and consider Relay or Bluevine for a small firm that needs a handful of sub-accounts.
How to choose
- Start with your state's trust rules. Find out which accounts you must hold, at what kind of bank, and how they need to be titled.
- List your entities. Count the management company, any maintenance or brokerage entities, and any property LLCs your principals own.
- Map maintenance spend. Decide which properties or crews need their own card group, budget, and merchant rules.
- Price your vendor payments. Multiply monthly ACH and wire counts by each provider's fees.
For head-to-head details, see Slash vs Mercury, Slash vs Bluevine, and Slash vs Chase, or how Slash handles multi-entity banking.
Apply in less than 10 minutes today
Join the 10,000+ businesses already using Slash.
Frequently Asked Questions
What is the best business bank account for a property management company?
For the management company's own operating account, Slash is a strong fit: virtual accounts per property or office, maintenance cards with merchant and spending limits, vendor bill pay with approvals, and accounting sync, for $0 or $25 a month per entity. Owner funds and security deposits usually belong in a trust account at a bank that meets your state's rules, such as Enterprise Bank & Trust.
Can I keep tenant security deposits or owner rent in a Slash account?
No. Slash accounts are intended for a business's own operating activity, and Slash can't support accounts that hold funds on behalf of third parties. Many states also require security deposits and owner funds in trust accounts with specific titling and bank requirements, so confirm your state's rules and keep those funds where state law requires.
Business Bank Accounts for Real Estate LLCs (2026)

What is the best business bank account for a company with multiple entities?
Look for one login across entities and a combined view. Slash holds unlimited entities under one login, each on its own $0 or $25 plan, with a Multi-Entity Overview of balances, spend, and statements. Relay also lets one login hold any number of US businesses, and Mercury links several companies to one profile.
What is the best business card for controlling spend across multiple locations and teams?
One with group-level rules. Slash card groups cap total spending across every card at a property or on a team, allow or block merchant categories and specific merchants, and set per-transaction limits, on both plans. The card settles daily from your Slash account and earns up to 2% cash back on eligible purchases.
Should each rental property have its own bank account?
It depends on who owns it. Property LLCs owned by you or your principals should each have their own account, and Slash can hold all of them under one login. For properties you manage for outside owners, whether owner funds can share one trust account with a ledger per owner, or need separate accounts, depends on your state's rules and your management agreements.
Top Fintech Platforms for Multi‐Entity Banking in 2026

Is a property management company's operating cash FDIC insured above $250,000?
Standard FDIC coverage is $250,000 per depositor at each insured bank. Slash offers FDIC insurance up to $200M through Column N.A. and the IntraFi sweep network, Mercury up to $5M, and Relay and Bluevine up to $3M each. Chase is a Member FDIC bank and doesn't publish extended coverage on its Business Complete Banking page.


