

What Are the Best Banking Platforms for Accounting Firms?
For accounting firms and bookkeepers, a banking platform's yield and monthly fee can matter less than how much cleanup it creates at month-end close, the process of reconciling each account's transactions and finalizing the books for the period. Much of that time goes to chasing receipts for unrecognized charges and recoding bank exports that don't match the client's chart of accounts.
A bookkeeper with 12 clients reconciles 12 sets of books, each against whatever that client's bank exports. The platforms below are compared on how much of that monthly work they can remove per client.
Platforms such as Slash are designed to cut that work. Each client keeps its own business banking¹ account, adds the firm as a team member and sends transactions to the ledger already categorized, and Slash's Accounting Partner Program gives the firm one login across every client on the platform.
Key Takeaways
- Slash sets no cap on virtual accounts on either plan, each with its own account and routing numbers. Mercury allows up to 100 checking and 100 savings accounts, Relay up to 20 checking accounts on Starter and Grow, and Bluevine 5 sub-accounts on Standard.
- Each client business opens and holds its own account and adds the firm as a user. On Slash, the Accountant role sees all transaction data but cannot create, delete or update users or cards.
- Slash, Relay, Mercury, Bluevine and Ramp each run a program for accounting firms with one login across clients and a referral fee per client.
- Platforms that sync categorized transactions to QuickBooks or Xero can cut the time spent exporting bank data and matching it to the ledger.
- Approval rules let one team member submit a payment and a named approver release it, so the firm can prepare payments without holding sole control of client funds.
Six Criteria That Change a Firm's Hours
The published feature lists across these five platforms read almost alike: checking, cards, bill pay, an accounting integration, some form of sub-account and a program for accountants. What separates them is the account limits and the workflow mechanics underneath those lists.
- Separate accounts inside one business: How many accounts with their own account and routing numbers a single business can hold, and whether a higher number requires a paid plan.
- Firm access: How the client adds the firm, what the firm's role can see and do, and whether one login covers every client.
- Approval routing: Whether one person can submit a payment and a second person releases it, with the platform recording both actions.
- Where the coding happens: Whether the platform codes transactions to the chart of accounts before they sync, or sends a raw export the bookkeeper matches by hand.
- Receipt capture: Whether the platform asks the cardholder for a receipt when the card is used, or leaves the firm to email them for it later.
- Client eligibility: Entity type and minimum balances, checked against the businesses the firm serves.
1. Slash: Best Overall for Clients Who Separate Funds by Property, Campaign or Reserve
Slash's Accounting Partner Program is built for firms that manage many clients. The firm gets one accounting login across every client through multi-entity support, and a referral fee for each client that activates an account. More than 10,000 businesses use Slash, which raised a $100M Series C at a $1.4B valuation in April 2026.
Each client applies as the business and holds its own account. The client's Owner adds the firm from Settings on the Accountant role, which sees all transaction data but cannot create, delete or update users or cards, or on a custom role the client defines. Deposits are FDIC-insured² up to $150 million through a sweep network of partner banks.
What Slash Changes Inside a Client's Books
- Unlimited virtual accounts: Separate accounts inside the client's main account, with no cap on either plan. Each has its own account and routing numbers and a nickname such as Payroll Reserve or Taxes, so a property manager separating funds by property, or an agency separating budgets by campaign, never reaches a published limit.
- One login across clients: The firm switches between client businesses from a single login, with access set per client, so the firm can hold Admin access on one client and view-only access on another.
- Approval rules set by the client: An Owner or Admin sets a dollar threshold, the number of reviews and the reviewers, by role or by name. A team member submits the transfer, and it stays pending until the reviewers approve it.
- Coding before the ledger: Mapping rules code each transaction to the chart of accounts in real time, and Slash syncs the coded transaction.
- Accounting integrations: QuickBooks Online, Xero, Sage Intacct and NetSuite, which covers clients whose reporting outgrew a small-business ledger.
- Receipts requested at the purchase: Slash texts the cardholder to upload a receipt after an in-person purchase, instead of leaving the firm to request it weeks later.
- Unlimited virtual cards on both plans: One card per vendor or engagement, each with its own spend limit, per-transaction ceiling and merchant restriction. Physical cards are available for any team member.
- Bill Pay with approval rules: Slash parses each invoice into vendor, number, dates and line items, then routes it for approval before anyone pays it.
Casey Woodard, Founder of Divine IO and a Slash customer, described the consolidation plainly. "I'm no longer having to use some weird cocktail of a million different things..." (slash.com/customers)
What It Costs
Slash publishes both plans on its pricing page instead of quoting per customer, which matters when you explain the cost to a client. Free costs $0 a month and pays up to 1.5% cashback, with same-day ACH at $1, domestic wires at $6 and outgoing FedNow or RTP at $5. Pro costs $25 a month, pays up to 2% cashback, and charges $0 for all three of those transfers.
Firms in the partner program earn $500 per activated client at the Partner and Silver tiers, $750 at Gold after five referrals and $1,000 at Platinum after ten.
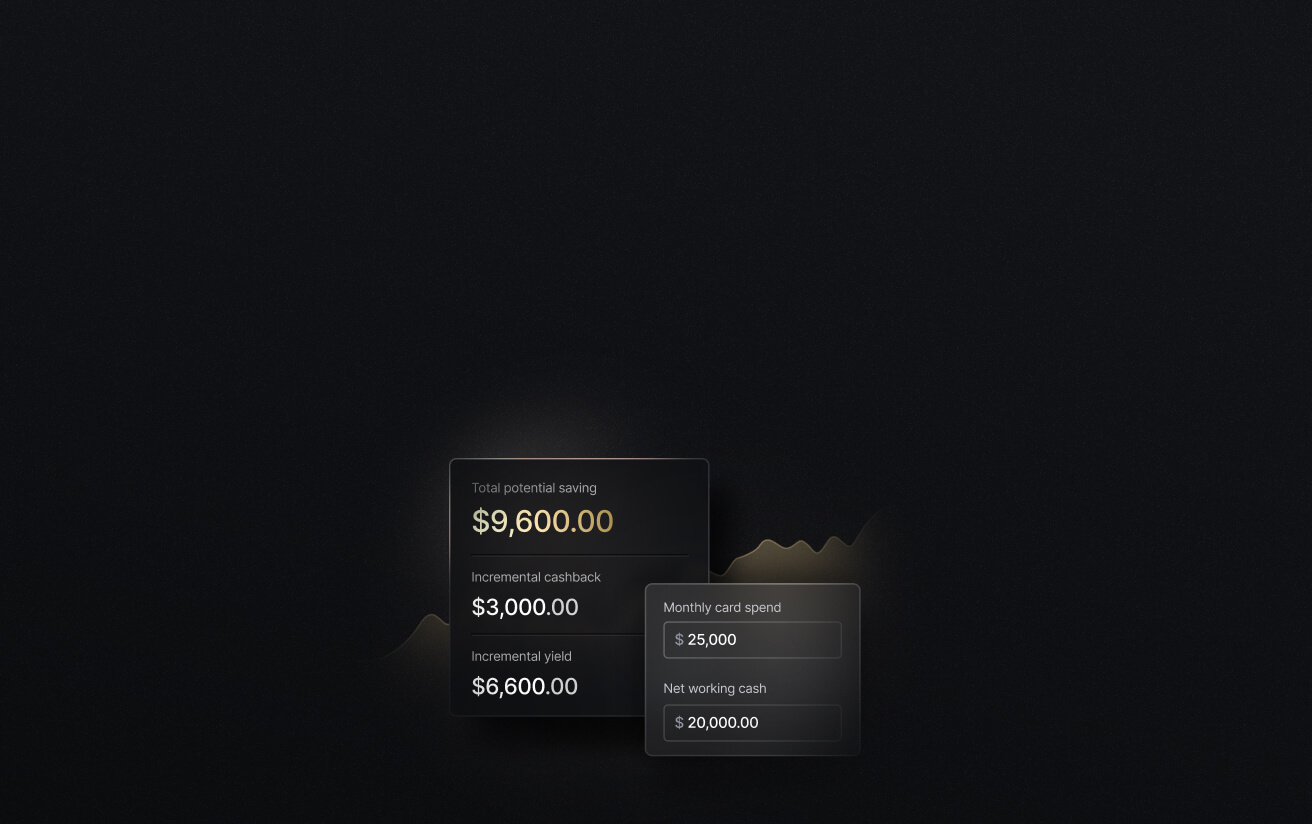
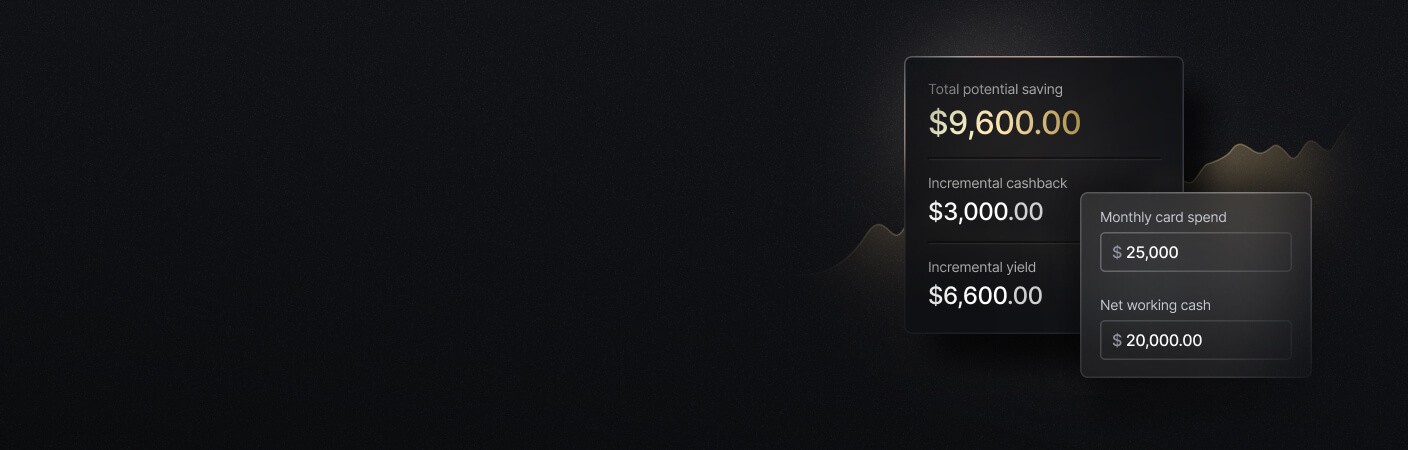
See the ROI behind your spend
Use this calculator to understand impact, then manage and track it all in Slash.
2. Relay: A Fit for Firms Running Profit First With Their Clients
Relay allocates income across named accounts, which maps onto the Profit First method. Thread Bank is the partner bank, with FDIC sweep coverage up to $3 million.
Relay's advisor partner program gives a firm a Partner Portal with a single login across all client banking, and pays $50 to $300 per client onboarded.
Per Relay's pricing page, a business can open up to 20 checking accounts on Starter and Grow, each with its own account and routing numbers, and up to 50 on Scale. Starter costs $0 and Grow $30 a month, and Scale lists at $120 with a limited-time price of $90.
A property manager holding deposits per property, or an agency holding a budget per campaign, can need more than 20 accounts, and reaching 50 means the Scale plan. On the ledger side, Relay integrates with QuickBooks Online and Xero and lists neither Sage Intacct nor NetSuite, so a client reporting in either one needs a separate export.
3. Mercury: A Fit for Firms Whose Clients Are Venture-Backed
A firm whose clients are funded startups may already work with Mercury. Mercury for accounting firms gives partner firms an Advisor Portal for client management, free Mercury Pro and referral bonuses of up to $1,500, terms apply.
A business can open up to 100 checking and 100 savings accounts, each with a unique account number, at no additional cost. Plans cost $0, $29.90 for Plus and $299 for Pro a month per Mercury's pricing page. NetSuite bank feeds are free on every plan, and NetSuite categorizations come with Pro.
Per Mercury's IO page, Mercury calculates the card limit from the balances a client holds with Mercury plus any external accounts the client links. Newer customers on lower balances repay daily, and monthly repayment becomes available once balances reach $15,000. A client asking when to move cash has to weigh the effect on the card limit too.
4. Bluevine: A Fit for Firms Whose Clients Need Credit Beside the Account
Bluevine offers business checking through Coastal Community Bank and a line of credit up to $250,000 issued by Celtic Bank, which suits clients who borrow against seasonal swings instead of raising equity. Its Accountant Partner Program gives firms single sign-on to all their clients' accounts and a bonus per qualified referral of up to $200, $250 or $300 by tier.
Per Bluevine's plans and pricing page, Standard allows 5 sub-accounts, Plus allows 10 and Premier allows 50, at $0, $30 and $95 a month. Coastal and its program banks carry FDIC coverage to $3 million.
A client that separates funds by property, campaign or job can need more than five sub-accounts, which puts it on a paid tier unless it meets the balance and card-spend waiver thresholds.
5. Ramp: A Fit for Firms Whose Clients Need Controls More Than Accounts
Ramp leads with spend management. It blocks out-of-policy spend before the charge, prompts for receipts at swipe, and surfaces exceptions for review. Its accounting partner program gives firms one portal across clients, the Advisor Console, and referral bonuses of $500 or $750 by tier, where eligible. The base plan is free, funded by interchange.
Ramp also offers a Ramp Checking Account held at First Internet Bank of Indiana, with dedicated account and routing numbers and multiple accounts per entity. Ramp publishes no cap on how many.
Per Ramp's application requirements, a business needs at least $25,000 in cash in a US business bank account, and Ramp accepts corporations, LLCs and limited partnerships. Clients below that balance do not qualify.
Side-by-Side Comparison
Provider figures reflect publicly published information as of September 2026 and are subject to change.
How to Pick the Platform to Recommend to Clients
Work through these in order, since an earlier question can rule a platform out.
- Check eligibility for each client: A $25,000 cash minimum or an entity-type rule rules out some businesses before any feature comparison.
- Count the accounts each client needs: A client separating funds by property, campaign or tax reserve needs a limit that covers that count on the plan it pays for.
- Check what the firm's role can do: Look for a role that sees every transaction without being able to move money, and a login that reaches every client.
- Ask where the coding happens: A transaction that arrives in the ledger mapped to the chart of accounts needs no export and no manual match.
- Check the approval rules: One team member submits a payment, a named approver releases it, and the platform records both actions.
Then run your own numbers. If reconciliation takes two hours a month per client, twelve clients is 24 hours, or $1,800 a month of billable time at a $75 rate. A $25 plan such as Slash Pro costs $300 a year against a $0 plan. On the card, a client spending $60,000 a month earns up to $900 back on Free at up to 1.5% and up to $1,200 on Pro at up to 2%, so Pro covers its $300 in the first month and earns up to $3,600 more than Free over the year.
Putting Slash to Work Across the Businesses You Serve
A client who banks in one place, pays bills in a second and holds reserves in a third leaves the firm reconciling across three systems. Running all of them on one platform removes that work.
- Each client opens its own account: The client applies as the business, then adds the firm on the Accountant role or a custom role from Settings.
- Reach every client from one login: Through the Accounting Partner Program, the firm manages each client from one accounting login.
- Open accounts by purpose: One virtual account per property, campaign, retainer or tax reserve, each with its own numbers.
- Issue a card per vendor:Virtual cards carry their own limits and merchant restrictions, so an unfamiliar charge identifies itself.
- Set the mapping rules once: Slash codes each transaction to the chart of accounts as it happens, so what syncs out is already categorized.
- Route the invoices: Bill Pay parses the invoice and holds it for approval before payment.
- Hold reserves in the same place: A treasury account⁶ backed by money market funds from Morgan Stanley and BlackRock, with no minimum balance, and Working Capital Financing⁵ on 30, 60 or 90-day terms in the same dashboard.
Conclusion
Five criteria decide the choice: eligibility, the account count each client needs, what the firm's role can see, where the platform codes transactions, and whether approval rules split submission from release. At a $75 billing rate, the reconciliation hours in the example above cost a firm more than the difference in plan fees.
On those criteria, a platform covering banking, cards, bill pay and reserves ranks ahead of one covering a single function, because each function it adds is one less system to reconcile.
Talk to the Slash team about bringing your clients onto Slash.
Apply in less than 10 minutes today
Join the 10,000+ businesses already using Slash.
FAQs
1. What should an accounting firm look for in a banking platform?
An accounting firm should look for five things: separate accounts without a low limit, a firm role that sees every transaction, approval rules that split submission from release, coding that happens before the ledger, and one login across clients. Eligibility comes first, since entity type and minimum balances rule clients out before any feature matters.
Online Banking Systems: Guide to Digital Banking Platforms

2. Can an accounting firm manage several clients' Slash accounts from one login?
An accounting firm can manage several clients' Slash accounts from one login through Slash's Accounting Partner Program and multi-entity support. Each client opens its own account and adds the firm as a team member, and access is set per client.
Top Fintech Platforms for Multi‐Entity Banking in 2026

3. Does Slash integrate with the accounting software a firm already uses?
Slash integrates with QuickBooks Online, Xero, Sage Intacct and NetSuite. Mapping rules code each transaction against the chart of accounts inside Slash before it syncs, so the ledger receives a categorized transaction.
Top Xero Integrations to Simplify Accounting and Cash Flow

Accounting Reconciliation: Types, Process & Best Practices
4. How many virtual accounts can a client open on Slash?
A client can open as many virtual accounts as it needs on Slash, on either plan, since Slash sets no cap. The client's Owner or Admin creates them, each gets its own account and routing numbers, and a firm on the Accountant role can see every account's balances and transactions.
5. Does Slash cost more than a free business checking account?
Slash publishes a $0 Free plan alongside $25 Pro, so it need not cost more. Pro costs $300 a year and raises cashback from up to 1.5% to up to 2%. A client spending $5,000 a month on cards earns up to $300 more a year on Pro, which covers the fee.
The 8 Best Free Business Bank Accounts in 2026


