

Stripe Alternatives: 5 Payment Processing Options for 2026
With more than 5 million businesses and 1.2 million websites using its software, Stripe is one of the largest payment service providers (PSPs) available today. With Stripe, a business can add a hosted checkout, subscriptions, or marketplace payouts without using a separate provider for every part of the transaction.
That said, it doesn’t fit every use case. A local retailer may want a simpler point-of-sale system, or a high-volume merchant may prefer a cheaper pricing structure. The right Stripe alternative ultimately depends on the problem you need to solve.
Keep reading to learn how Stripe works, who it serves, and what other payment processors might be a better match for your business. One of the best options among these is Slash, a financial platform that ties business banking, payment processing, expense management, and more together on one real time dashboard.¹
The standard in finance
Slash goes above with better controls, better rewards, and better support for your business.
Key Takeaways
- Stripe's headline 2.9% plus 30 cents covers the base payment. Manual entry adds 0.5%, international cards add 1.5%, currency conversion adds 1%, and BNPL options like Klarna run 5.99% plus 30 cents.
- Stripe's dispute economics are punishing for merchants with frequent chargebacks: $15 to receive a dispute, $15 more to fight it, and 30% of the amount you win.
- Stripe Tax calculates, but doesn't assume, liability, so your remittance and audit responsibility stay with your business unless you move to a merchant of record.
- Stripe maintains a longer restricted-business list than most merchants expect, which makes eligibility worth checking before you build anything.
- Slash and Paddle are merchant of record platforms, while most other options aren’t.
What Is Stripe, and How Does It Work?
Stripe is a financial infrastructure platform that lets businesses accept payments online, in person, and across most international markets. Its core “Payments” product connects a checkout page, app, payment link, invoice, and/or terminal to the card networks and banking systems that authorize and settle the transaction. When someone makes a purchase, Stripe places the revenue into the merchant’s balance and pays out to a connected bank account.
Their real specialty is online card acceptance. If you want your own payment page, Checkout provides a prebuilt template, while Elements supplies components for a customized experience. Payment Links lets you skip the checkout step entirely, as you can instead send links directly to your customers. If you have exclusively in-person operations, you can also get a terminal starting at $59, along with associated fees.
Stripe comes with plenty of other products outside of the card acceptance step. Billing manages subscriptions and usage-based pricing, while Invoicing supports one-time and recurring invoices. Connect lets you onboard sellers, divide payments, and issue payouts. Stripe also offers a separate AI-powered security tool called Radar, which provides fraud controls for $10/mo plus $0.05 per transaction on its Standard plan.
Stripe fees and pricing
The standard U.S. pricing model is “pay as you go”, with no setup or monthly fee for basic Payments. Stripe charges 2.9% plus 30 cents for a successful domestic card transaction. Manually entered cards add 0.5%, international cards add 1.5%, and currency conversion adds another 1%. The heftiest fee stems from Buy Now Pay Later options like Klarna, which come with a 5.99% plus 30 cent fee. Larger businesses can request custom pricing, including interchange-plus terms and volume discounts.
It’s important to note that those numbers cover the payment itself, not every Stripe product. Billing, Tax, Invoicing, Connect, advanced fraud tools, instant payouts, and other services may carry separate charges. Overall, you’ll have to know your business’s complete workflow to get a full understanding of the total price.
As far as market coverage is concerned, Stripe advertises more than 125 payment methods, cardholder support in over 195 countries, and processing in more than 135 currencies.
Who Uses Stripe?
Stripe serves companies ranging from new online stores to large enterprises. Ecommerce merchants can use it for cards, wallets, and bank payments, and SaaS businesses might use Billing for recurring and usage-based plans. Marketplaces and software platforms can use Connect to onboard merchants and embed payments, while retailers may join online and physical transactions through Terminal.
That range is valuable for businesses expecting their model to shift over time. A company might begin with a payment link, add subscriptions, expand internationally, and eventually build a marketplace without replacing its provider along the way.
Why Do Businesses Look for Stripe Alternatives?
Stripe covers a good variety of use cases, but its wide reach comes with a few tradeoffs. You may want to research alternatives for the following reasons:
- The total price can be higher than you expect: International-card, currency-conversion, manually entered payment, instant-payout, and product-specific fees can and will add up. If you commonly fight chargebacks, there’s another set of fees you should be aware of: a $15 dispute fee when a customer files a chargeback, and another $15 fee to fight it. If you win, Stripe takes a 30% cut. That’s a lot.
- The platform can be more technical than necessary: Stripe’s strength is in its APIs and configuration, but not everyone’s interested in that kind of flexibility. A restaurant or retailer may prefer a provider with a ready-made POS, inventory, scheduling, and staff-management system rather than one they need to put work into building.
- You’ve still got the obligations: With Stripe Tax, your business retains responsibility for tax remittance and audits. Stripe offers Managed Payments, which can assume those duties for supported digital-goods transactions, but it’s a separate product. Companies wanting that model by default may want to look for a merchant of record (MoR), which is the legal entity responsible for accepting the liability for all transactions.
- Not every business category qualifies: There’s a surprisingly long list of businesses and services that Stripe doesn’t support, seen here. Among these are companies that offer engineering services, IT design, adult content, gambling, debt relief, and quite a few other categories that you might otherwise expect to be covered.
Top Stripe Alternatives in 2026
The payment services provider you choose may largely depend on the kind of business you operate and the average level of volume you see on a daily basis. Here are our five picks for leading Stripe alternatives in 2026:
Slash
Slash is a managed merchant of record solution that offers both business banking tools and payment processing solutions for online businesses. Whether you want to accept cards through Slash Invoicing or build custom web checkout and payment flows with the help of Slash’s SDK, you’ll be set up to accept more payments from your customers without having to add several extra pieces of software.
One of the platform’s biggest strengths is its reach beyond payment processing. As an all-in-one financial solution, Slash users also get access to working capital lines of credit, stablecoin rails, high-yield treasury, and expense management features.⁴,⁵,⁶ You can also issue unlimited physical and virtual Visa® Platinum Cards, each earning up to 2% cash back on eligible purchases.
- Strength: Slash is one of the only options available that ties merchant services together with a business checking account and corporate card program. Additionally, you won’t pay a high upcharge for its merchant of record services.
- Weakness: At this time, Slash doesn’t support payment processing for in-person purchases.
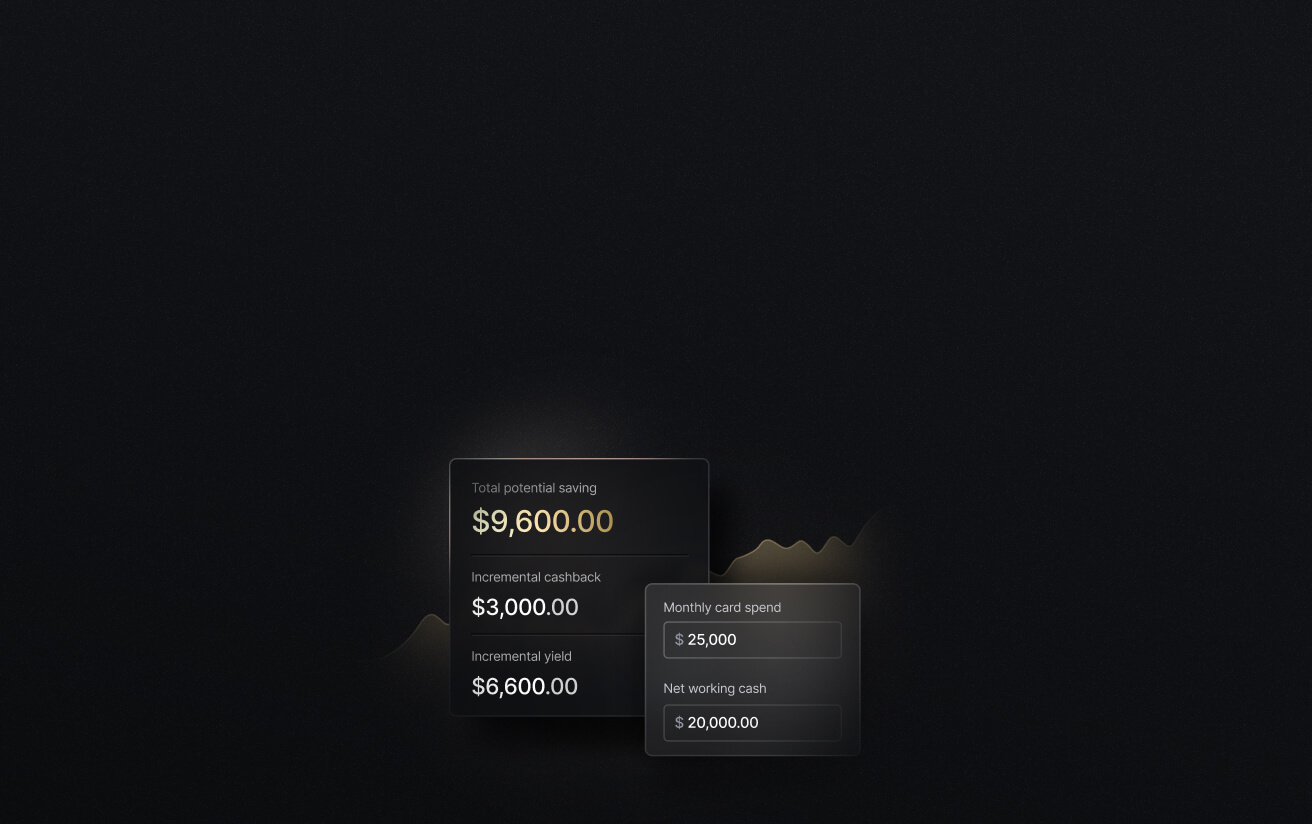
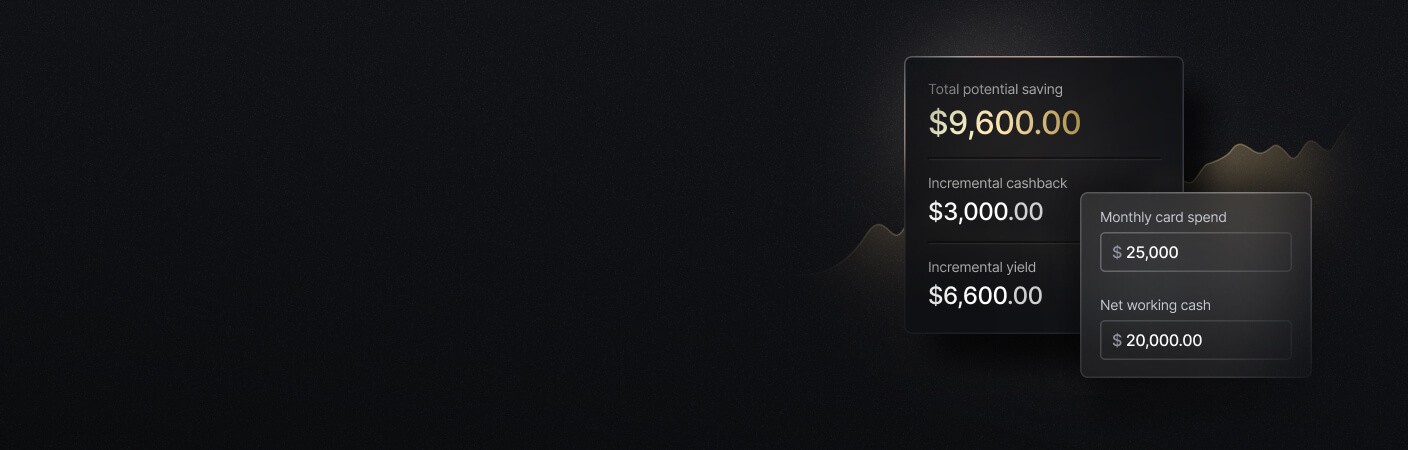
See the ROI behind your spend
Use this calculator to understand impact, then manage and track it all in Slash.
Checkout.com
Checkout.com is an enterprise payment platform for businesses that process online sales across several markets. It combines gateway services, acquiring, payouts, fraud prevention, authentication, identity verification, and payment optimization in one stack. Merchants can accept major cards and local payment methods on hosted payment pages or a customized checkout. Users can also use Checkout.com’s dashboard to monitor balances and transactions in real time, similarly to Slash.
- Strength: Checkout.com comes with a unique feature called Intelligent Acceptance, which is designed to improve authorization rates, control fraud, and optimize individual transactions using AI.
- Weakness: The platform covers 57 countries and over 150 currencies, which falls short of the worldwide coverage that Stripe supports.
Square
Square is the most approachable alternative for businesses that sell in person as well as online. Its platform combines card processing with readers, terminals, registers, point-of-sale software, online stores, invoices, select banking products, and more. Its physical hardware is especially user-friendly, which is a large part of the reason it holds the largest share of the point-of-sale system market.
On Square’s free plan, you’ll be charged 2.6% plus 15 cents for tapped or swiped payments and 3.3% plus 30 cents online. If you’d prefer lower fees per transaction, you could also choose a $49/mo or $149/mo subscription plan.
- Strength: Square provides a cohesive, ready-to-use system for hardware, POS, ecommerce, and payments. It also offers a business checking account, which most PSPs don’t come with.
- Weakness: Its strengths are built around everyday merchant operations. If you need more global routing capabilities or complex marketplace payments, the platforms that allow you to customize your experience more deeply may be a better fit.
Adyen
Adyen is a global enterprise platform that covers online, mobile, and in-person payments. While their international coverage is a little short of Stripe’s, it’s still a strength; they cover over 130 countries and 150 currencies, and they’ve actually built out their own acquiring banks in certain global markets.
Their API connects payment acceptance, local methods, risk management, authentication, payouts, data, and embedded financial products. Adyen’s pricing structure is interchange-plus rather than flat-rate, making it a solid fit for higher-volume businesses.
- Strength: Along with its payment services, Adyen offers several other financial features, including working capital financing and corporate card issuing.
- Weakness: Its large scale and focus on global enterprises can be a bit much for a smaller merchant that’s just looking for a hosted checkout or basic card processing.
Paddle
Paddle’s main strength is the fact that it operates as a merchant of record for SaaS companies and other online businesses. It handles checkout, payments, subscription management, invoicing, dunning, reporting, sales-tax calculation, tax remittance, and financial compliance. Rather than simply processing a transaction, Paddle becomes the legal seller to the end customer and then pays the software business its proceeds, just like Slash.
In exchange for the shifting of responsibility, Paddle charges a high per-transaction fee of 5% plus 50 cents. If you’d strongly prefer tax responsibilities and liability to be off your plate, though, that extra cost could be worth it.
- Strength: Paddle removes substantial tax, compliance, chargeback, payment, and subscription-administration work, making international expansion easier for online companies.
- Weakness: It doesn’t offer in-person products for brick-and-mortar stores, and the fees are higher than any other competitor on this list.
Make the Right Financial Move with Slash
With Slash, you get corporate cards, expense management features, automated invoicing, and a lot more in the same place that contains your payment gateway and credit card processor. You also get merchant of record services without the substantial upcharge that comes with providers like Paddle.
Qualifying Slash users can access payment processing via native card acceptance in Slash Invoicing and/or a custom web gateway with the help of our SDK. Either way, you can view invoice and checkout payments in the one dashboard, issue partial refunds, track processed funds into Slash accounts, and more.
Since we function as a merchant of record, we ultimately process the payment, take full financial and legal liability, and handle compliance. Normally, this results in per-transaction fees in the range of 4-10%. However, Slash only charges a flat fee of 3% plus 40 cents per transaction, with no monthly subscription cost.
Along with your payment processor and gateway, Slash also gives you access to the following features:
- High-yield treasury: Earn up to 4.01% annualized yield on idle funds with money market investments from BlackRock and Morgan Stanley, managed directly within your Slash account.
- Business banking: Create multiple business bank accounts to silo cash flows by project, department, or client with real-time analytics across each of them. Up to $150M in FDIC insurance coverage from the Column N.A. insured cash sweep network.²
- The Slash Visa® Platinum Card: The Slash Card is a corporate charge card that allows you to set customizable spending controls and issue unlimited virtual cards for handling team expenses, vendor payments, subscriptions, and more. Users can also earn up to 2% cash back on eligible business purchases.
- Multiple payment methods: Slash supports same day ACH, international wire transfers to over 180 countries via SWIFT, real-time payments through RTP and FedNow, and stablecoin payments in USDC or USDT.
- Accounting automation: Transactions are categorized as they post and carry the accounting dimensions your ledger expects: GL codes, departments, classes, locations, subsidiaries, vendor details, cardholder memos, and receipts. Set your mapping rules once in Slash instead of reclassifying spend at close.
Apply in less than 10 minutes today
Join the 10,000+ businesses already using Slash.
Frequently Asked Questions
What is a merchant of record?
A merchant of record is technically the legal entity that sells to your customer, which means it appears on your statement, collects and remits sales tax and VAT, and carries liability for chargebacks and compliance. You still deliver the product, but the transaction legally belongs to the provider, who then pays you your proceeds.
MoR providers typically charge well above a standard processing rate in exchange for absorbing that extra exposure. While Slash’s payment processing product functions as an MoR, users are still required to calculate their own sales tax.
Best Merchant Services Providers in 2026 Compared

What pricing structures can payment processors come with?
- Flat-rate charges one percentage plus a fixed amount on every transaction regardless of card type, which is best for lower volumes.
- Interchange-plus passes through the card network's actual cost and adds a disclosed markup, which is more transparent and typically cheaper as volume grows.
- Subscription pricing replaces the percentage markup with a monthly fee plus a small per-transaction charge.
- Tieredpricing sorts transactions into categories you can't identify until later, which makes it tough to forecast.
Is Stripe better for online or in-person merchants?
Stripe’s strengths skew more towards online merchants, since features like Checkout and Elements are meant for web customization. That said, it fits both use cases well.
E-commerce Accounting Guide for Online Businesses

Read more from us


