

The Leading Business Bank Accounts for Marketing Teams
Marketing agencies don’t handle money like your average local business. They often earn revenue through monthly retainers and performance-based contracts, and their expenses include things like software subscriptions, contractor payments, and advertising budgets rather than inventory. Since that sort of income can be inconsistent, cash flows can be tough to wrangle.
The best business bank accounts offer features that can help agencies deal with those sorts of challenges. We wrote this guide to help break down what marketing professionals should look for in a bank account and which of today’s leading providers may be the right choice for your agency. If you need to do more with your money than earmark it for certain advertising expenses, you should consider Slash. With deep expense management features, subaccounts, a high-yield treasury account, and up to 5% cashback on AppLovin ad spend, Slash is the right choice for modern marketing agencies.¹,⁶
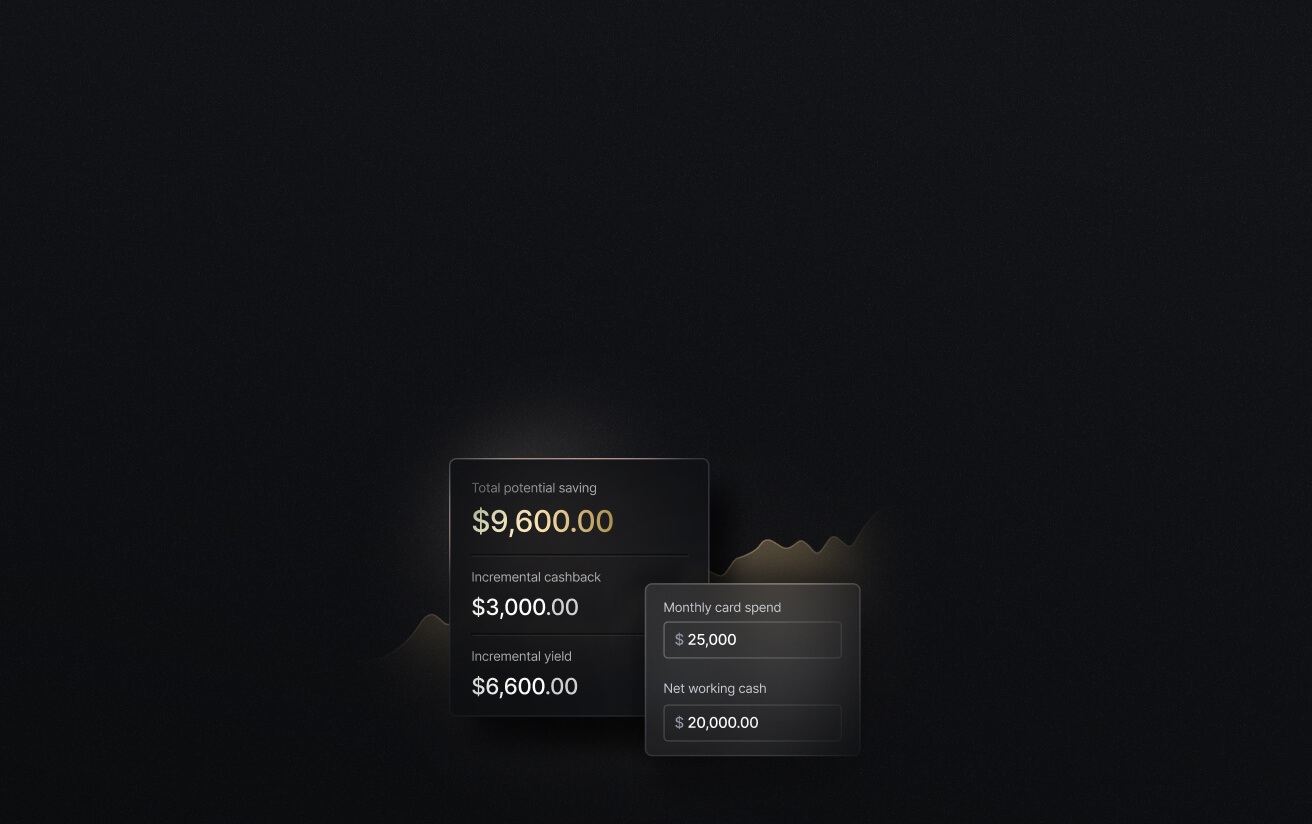
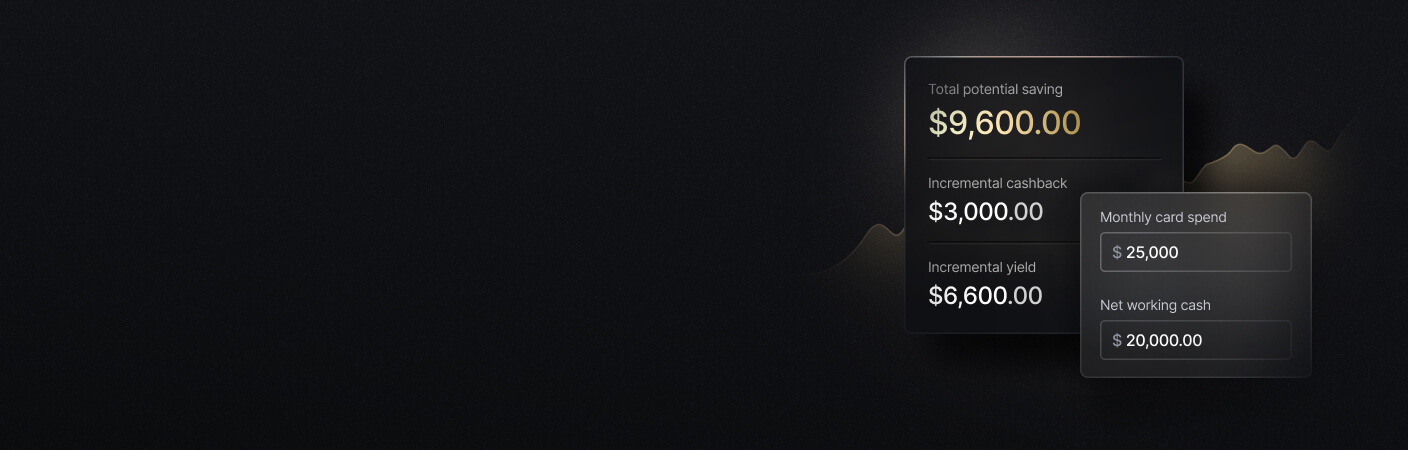
See the ROI behind your spend
Use this calculator to understand impact, then manage and track it all in Slash.
Key Takeaways
- A marketing agency’s payroll, contractors, and ad platforms run on fixed schedules while their clients usually pay on their own time.
- Novo limits each user to one physical and one virtual card, and every user receives full account access, which makes it a poor fit for large teams.
- Mercury’s Treasury product requires at least $250,000 in actively held balances, and the platform is unavailable to founders in certain parts of the world.
- Relay’s multiple checking accounts aren’t too different from Slash’s subaccounts, even though they carry different names.
- For qualifying businesses, Slash offers up to 5% cashback on AppLovin ad spend made through the Slash Card.
How Marketing Agencies Use Business Bank Accounts
Every business needs an account for receiving payments and covering operating expenses, but if you run a marketing agency, you’ll need more than basic checking. Client work creates a mixture of agency expenses and client-billable costs. An employee might purchase ad inventory, book travel for a shoot, subscribe to a design tool, or hire a freelancer. If these transactions all flow through the same card without labels or controls, it’ll be a nightmare to reconstruct which client owes what at the end of the month.
Cash flow is also tricky. You probably pay your employees, contractors, and advertising platforms on a fixed schedule, while clients may take anywhere between 1 and 60 days to pay you. A delayed invoice can leave you covering expenses from your agency’s own reserves. Real-time balance information and faster payment methods can help teams spot those gaps and seal them up sooner.
Unlike most businesses, agencies grow by adding people rather than inventory. That means they’ll likely need customizable employee cards and approval workflows. A creative director may want a card for simple production expenses, while a media buyer might require a much larger limit for advertising. With Slash, you can issue unlimited virtual and physical cards with their own limits and restrictions, and you can also automate approval workflows when predetermined thresholds are met.
Today’s marketing teams should look for banking platforms that can connect all these activities automatically. Transactions should sync to accounting software, receipts should be attached to card purchases, and spending should be categorized by client or campaign. This type of automation doesn’t remove the need for oversight, but it can save you lots of time on manual work.
How to Choose the Right Bank Account
While a three-person design studio has different requirements from a media agency processing millions in annual ad spend, a lot of banking features can help both teams in similar ways. These are the main things you should keep an eye out for:
- Cashback on advertising: Some agencies that run ads on behalf of clients spend that money through corporate cards. Cashback can turn that spending into meaningful value, particularly when there’s a category-based bonus for marketing expenses..
- Expense management tools: Look for customizable spending limits, merchant restrictions, approval workflows, receipt collection, and real-time alerts.
- Range of payment methods: In addition to paying contractors and taking in revenue, marketing agencies often have to accept money from their clients that’s meant for ad spend. The more payment rails your platform supports for all these transfers, the better. Along with traditional methods, Slash comes with built-in crypto on/off ramps, meaning forward-thinking teams can save time and money by sending and receiving stablecoins.⁴
- Subaccounts: Subaccounts are like small bank accounts meant to organize money by purpose. An agency might maintain different subaccounts for operating expenses, payroll, taxes, reserves, and individual client budgets.
- Fee structures and limits: None of these tools matter if the total cost is out of your price range. Review transaction fees, minimum-balance requirements, the price of card issuance, and the monthly subscription cost. Keep an eye out for pricing that increases with the number of users or cards, since a low starting price can become expensive as you start growing.
All in all, the best choice is usually the account that makes your day-to-day life easier. A paid-media agency may prioritize card rewards and spending capacity, while a firm with a bunch of freelancers may care more about low-cost payments and approval controls.
The Leading Business Bank Accounts for Marketing Agencies
As you shop for a business banking solution, it can feel like there’s way too much to choose from. To help clear everything up, we’ve arranged six of today’s top options and compared them based on their main features, strengths, and weaknesses:
Slash
Slash is a financial platform built to help marketing agencies with unlimited subaccounts, deep expense tracking features, and support for credit card processing within invoices. With the Slash Visa® Platinum Card, you can also earn up to 2% cashback on eligible business expenses. Your pending invoices, expenses, virtual accounts, assigned actions, and more are all visible on our real time dashboard.
If your marketing team is running on thin margins, we understand that you might want a little extra juice from your rewards. That’s why Slash is now offering up to 5% cashback on eligible AppLovin ad spend made with the Slash Card. If you already use AppLovin for digital ads, you can earn extra capital without changing anything about the way you spend your money.
- Strength: Slash is the only option on this list that combines high cashback, payment processing, and stablecoin support with a full business banking platform.
- Weakness: At this time, Slash doesn’t support sole proprietorships.
Bluevine
Bluevine’s main differentiator is the interest it offers on checking balances, which varies across three plans. Standard has no monthly fee and includes up to five subaccounts, unlimited transactions, free standard ACH transfers, invoicing, and a 1.3% APY for eligible customers. Plus costs $30 per month and raises the APY to 1.75%, while Premier costs $95 and offers a 3.0% APY on all balances, up to 50 subaccounts, and larger payment-fee discounts. Like Slash, Bluevine also offers working capital lines of credit to eligible customers.
- Strength: Bluevine is one of the only platforms you’ll find that pays interest directly on checking balances. Additionally, their Business Debit Mastercard earns up to 4% cashback at specific merchants.
- Weakness: If you want more than five subaccounts, you’ll have to subscribe to a paid plan. Additionally, not only does Bluevine lack crypto support, but they also don’t do business with companies “engaged with cryptocurrency” according to their terms.
Mercury
Mercury combines business checking and savings with cards, invoicing, bill pay, expense management, and accounting integrations. Its core account costs $0 per month with no minimum balance, and comes with those basic features. Mercury Plus ($35/mo) gives you ACH debits and recurring invoices, and Mercury Pro ($350/mo) adds a relationship manager and more advanced workflows. The platform offers free USD payments through ACH, wires, checks, and RTP, plus 1.5% cashback on eligible spend through the Mercury IO card.
- Strength: Mercury’s domestic and international USD wire transfers don’t come with a sending fee, which is a savings opportunity for businesses that rely on SWIFT to send money.
- Weakness: Access to their Treasury product requires at least $250,000 in actively-held balances. Also, business owners across southeast Asia, Pakistan, Belarus, and much of Africa cannot open a Mercury account.
Novo
As one of the simplest options on this list, Novo offers a single business checking account with no monthly maintenance fee, minimum balance, or transaction limit. The account includes standard ACH transfers, invoicing, expense tracking, mobile check deposit, integrations, and Reserves for separating money within the main account. Novo also offers physical and virtual debit cards alongside a business credit card that earns 1% cashback, or 2% when the business maintains at least $5,000 in checking.
While these features are suitable for a small business, they aren’t quite built to scale. With Novo, you’re only allowed to issue one physical card and one virtual card per user. Each of these users gets full account access and control, meaning it’s unrealistic to bring each of your employees aboard.
- Strength: Novo includes more features for free than most competitors, including invoicing, bookkeeping features, and Reserves.
- Weakness: Novo’s toolset isn’t a good fit for mid-sized marketing agencies. Balances are only FDIC-insured up to $250,000, and API access isn’t supported.
Relay
One of the main things you’ll see Relay advertise is its support for up to 50 full checking accounts, each with their own account numbers. While that’s certainly helpful for expense management, they’re functionally no different from Slash’s subaccounts, which also come with unique account numbers.
Relay’s free Starter plan supports up to 20 checking accounts and two savings accounts, along with bill pay, invoicing, expense management, and accounting connections. Grow costs $30 per month and adds stronger approval and payment workflows, while the $120 Scale increases the limit to 50 checking accounts and brings higher savings yields and cashback.
- Strength: Relay allows businesses to add a credit card surcharge of up to 2.9% on customer invoices to help offset standard card processing fees, which is a helpful feature you won’t find with many other platforms.
- Weakness: The best yields, payment pricing, and workflow controls require a fairly high paid subscription of $120.
Chase Business
Alongside online banking and invoicing, Chase gives users access to about 5,000 branches and 14,000 ATMs. While most of the options above don’t support cash deposits, Chase is a good match for businesses that often accept cash from their customers.
Chase offers three main business checking tiers, ranging from $15 to $95 per month, each including built-in card acceptance and digital invoicing. When it comes to marketing expenses in particular, Chase’s Ink Business Preferred® Credit Card offers 3x points on social media and advertising spend, which surpasses most other competitors (depending on how you redeem the points). That card comes with a $95 annual fee.
- Strength: Chase offers in-person service and cash deposits, and the Ink Business Preferred Card’s 3x points offers a high rewards ceiling.
- Weakness: Their monthly fees and transaction allowances can make Chase more expensive and restrictive than other accounts that offer unlimited activity without waiver requirements.
Earn More Cashback on Ad Spend With Slash
Today’s marketing agencies need a combination of deep expense management, flexible invoicing, diverse payment rails, and high rewards on ad spend. That’s exactly what you’ll find with Slash.
Slash is a business banking platform that offers qualifying agencies up to 5% cashback on eligible AppLovin ad spend, and 2% back on other eligible business purchases. Our platform also comes with accounts payable/ receivable features and syncs with QuickBooks Online, Xero, Sage Intacct, and NetSuite. That means the hours invoiced through a time-tracking or accounting system can connect to your broader financial workflow. Client payments flow into Slash, bills and other obligations can be managed in the same spot, and bank and card activity can sync with your agency’s general ledger.
Slash can also help you better understand and control the costs behind your client work. You can issue unlimited virtual and physical Slash Cards for specific employees, departments, clients, or campaigns, each of which can come with their own individual restrictions and controls.
Marketing agencies can also take advantage of the following features:
- High-yield treasury: Earn up to 4.01% annualized yield on idle funds with money market investments from BlackRock and Morgan Stanley, managed directly within your Slash account.⁶
- Diverse payment rails: Slash supports a wide range of payment methods, including card spend, global ACH, international wire transfers to over 180 countries via SWIFT, and real-time domestic payments through RTP and FedNow.
- Payment processing: Let customers pay your invoices by card, add secure checkout components to your existing webpage, track payments from purchase to payout, and manage your incoming revenue from the Slash dashboard.
- Multi-entity support: Slash offers multi-entity account management tools without separate logins, allowing businesses to track spending, manage accounts, and download statements across all subsidiaries in one place.
- Business banking: FDIC-insured business checking, protected up to $150M through Column N.A.'s insured cash sweep network.²
Apply in less than 10 minutes today
Join the 10,000+ businesses already using Slash.
Frequently Asked Questions
How do marketing agencies bill their clients?
Most agencies use some mix of four structures: a monthly retainer for ongoing work, a fixed fee tied to a defined project, hourly billing for overflow or ad hoc requests, and performance-based arrangements tied to results. Media spend is usually handled separately from fees, either as a pass-through billed at cost or with a markup, or as a percentage of the ad budget managed.
Should agencies keep client ad budgets in a separate account?
It’s a good idea, yes. Money collected to spend on a client’s behalf generally isn’t your revenue, and mixing it with your operating cash makes it easy to overstate what you actually have. A dedicated subaccount per client, or at minimum one account for all pass-through media, keeps everything cleaner.
What Is a Sub-Account? Key Benefits, Features, and Use Cases

How do some platforms insure deposits beyond the $250k FDIC limit?
Through something called a sweep network. When you deposit more than $250,000 into a platform, the system can automatically split and "sweep" your cash across a network of multiple FDIC-insured partner banks. The more partner banks, the higher the limit.
FDIC Insurance Guide: Limits, Protection Strategies, and How to Elevate Your Coverage


