

Which Business Bank Accounts Are Best for Home Services and Trade Contractors in 2026?
Homeowner spending on improvements and maintenance is expected to reach roughly $522 billion by the end of 2026, according to the Harvard Joint Center for Housing Studies' Leading Indicator of Remodeling Activity. Slash runs a business banking platform for contractors¹ built for the trades doing that work, with per-job virtual cards, invoicing with embedded payment links, and Bill Pay in one dashboard.
That $522 billion moves through a very specific cash cycle. A contractor collects a deposit, buys materials on a card, pays subs on a Friday, waits on a progress payment, and repeats across four or five active jobs at once. The bank account either keeps those jobs separated and visible, or it turns month-end into a receipt hunt.
Most business banking reviews rank on APY and branch count. Neither one tells an HVAC company or a roofing crew whether they'll know which job is over budget before the final invoice goes out. Here's how five accounts compare on the criteria that actually run a trade business.
The standard in finance
Slash goes above with better controls, better rewards, and better support for your business.
Key Takeaways
- Slash issues unlimited virtual cards with per-job limits and merchant restrictions on both plans, so every crew purchase lands on the right job.
- Contractors should rank accounts on job-level spend control, invoicing speed, and how fast customer payments settle, not on APY.
- Cash deposit access still matters for some trades and is a legitimate reason to keep a traditional bank account alongside a platform.
- Working capital terms decide whether a contractor can start the next job before the last one pays.
- Entity type is the first filter: several platforms, including Slash, are open to LLCs and corporations but not sole proprietors.
What a Trade Business Actually Needs From a Bank Account
Five things decide it, and none of them are on a typical comparison chart.
- Job-level spend control: Can a crew lead buy materials on a card that only works at the supply house, with a limit set to that job's materials budget?
- Invoicing and collection: How fast can you send an invoice, and can the customer pay it by bank transfer without mailing a check?
- Bill pay with approvals: Do sub and supplier invoices route to an approver before payment, and does the invoice stay attached to the transaction?
- Cash and check handling: If you take cash or paper checks, how do they get in, and what does it cost?
- Working capital terms: When a $60,000 job needs $25,000 in materials before the deposit clears, where does that come from and on what terms?
1. Slash: Best Overall for Multi-Job Contractors
Slash is a financial technology company, with banking services provided by partner bank Column N.A. It raised a$100M Series C at a $1.4 billion valuation and, according to Slash, serves more than 10,000 businesses.
The reason it leads for contractors is that the platform treats a job the way a contractor does: as a budget with its own cards, its own purchases, and its own invoice.
What Slash Does for Trade Contractors
- One virtual card per job: Issue a card for each project from the corporate cards dashboard, set the limit to that job's materials budget, and restrict it to the supply houses your crews use. Physical cards are available for any team member who needs one.
- Card groups by crew or division: Roll job cards up into a group for Residential, Commercial, or a specific foreman, with a group ceiling so no one job can drain the month.
- Receipt capture from the truck: When a purchase needs a receipt, Twin, Slash's AI financial assistant, texts the cardholder for a photo and matches it to the transaction with OCR. No envelope of receipts on Friday.
- **Invoicing with payment links:** Generate a professional invoice from saved customer contacts, with line items, tax, and discounts formatted automatically. The customer pays by bank transfer from an embedded link, Slash sends automated reminders as the due date approaches, and recurring service contracts can carry ACH debit authorization.
- **Bill Pay for subs and suppliers:** Forward or upload a sub's invoice, Slash parses it into a digital bill, approval rules route it to the right person, and it pays on the scheduled date over ACH, RTP, or FedNow.
- **Working Capital Financing:** Approved businesses can draw short-term financing from the dashboard with 30-, 60-, or 90-day repayment terms, sized to a progress-payment schedule.⁵
- Unlimited virtual accounts: A separate checking account for tax reserves, deposits held, and operating cash, all FDIC-insured up to $150 million through Column N.A.'s insured cash sweep network.²
- Accounting sync: Two-way integrations with QuickBooks Online, Xero, NetSuite, and Sage Intacct, with transactions categorized and coded before they hit the ledger.
Orestes Romero, CFO of BuildPro Construction, a Slash customer running residential and commercial projects in Miami, described the setup on site: "At any given time, we can have five or six different virtual credit cards issued and given to our subcontractors or people working on site. They can purchase materials from different stores or vendors as needed." BuildPro reports roughly 40% less reconciliation work and 50+ active virtual cards.
Pricing
The Free plan is $0 a month with unlimited virtual cards, up to 1.5% cashback, and the full FDIC sweep. Domestic wires are $6, same-day ACH is $1, and outgoing FedNow or RTP is $5. Pro is $25 a month, raises cashback to up to 2%, and takes those three transfer types to $0.
Slash accounts are open to US-registered LLCs, C-Corps, and S-Corps. Sole proprietorships are not eligible, which matters for owner-operators who haven't formed an entity yet.
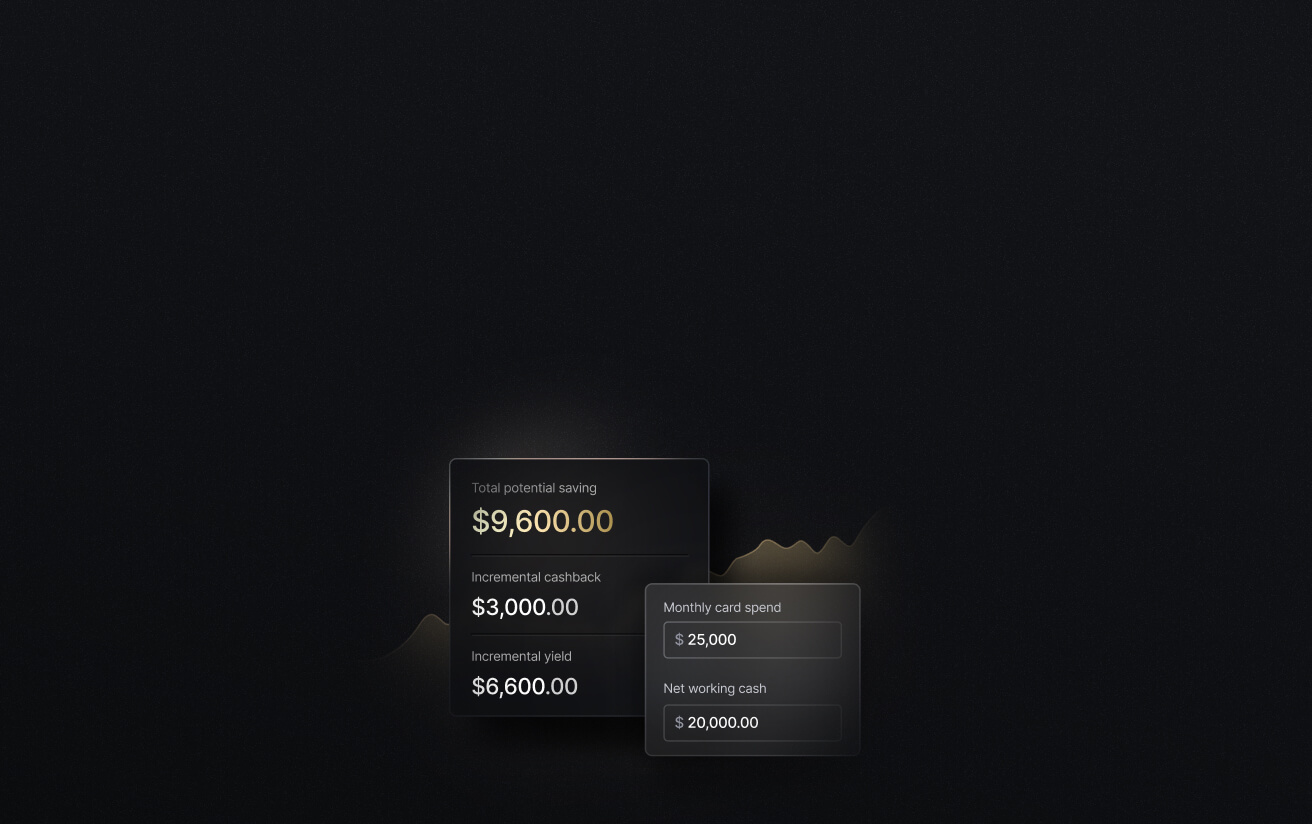
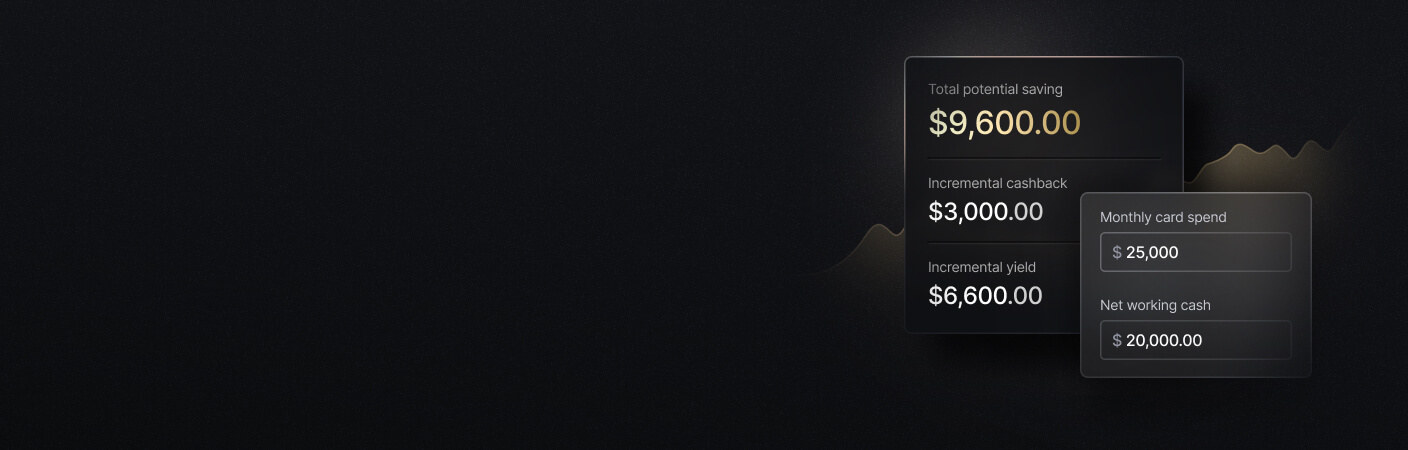
See the ROI behind your spend
Use this calculator to understand impact, then manage and track it all in Slash.
2. Relay: A Fit for Contractors Running Profit First
Relay turns one login into up to 20 checking accounts, each with its own routing and account number, which maps cleanly onto the Profit First allocation model many trade businesses use. Banking runs through Thread Bank with FDIC sweep coverage up to $3 million.
Per NerdWallet's Relay review, Starter is $0 a month, Grow is $30, and Scale runs $90 to $120. Relay caps issuance at 50 debit cards, and those are debit cards rather than a cashback charge card, so a contractor running a card per job across many active projects should count before committing.
Relay is a reasonable cash-organization layer and works best alongside a card program rather than as one.
3. Bluevine: A Fit for Contractors Who Want Checking Yield and a Credit Line
Bluevine is a financial technology company with banking services provided by Coastal Community Bank. Its business checking pairs with a revolving line of credit of up to $250,000, which is relevant for any contractor floating materials cost ahead of a deposit.
Bluevine added invoicing and payment links in 2026, and cash deposits are accepted at Green Dot retail locations, which third-party reviews report at$4.95 per deposit. Outgoing domestic wires run $15 on the standard plan, and standard ACH is free.
For a contractor with steady balances and occasional cash, that combination covers a lot. Check hold times on mobile check deposits, which reviewers have flagged as long.
4. Chase Business Complete Banking: A Fit for Cash-Heavy Trades That Want a Branch
Chase Business Complete Banking is the entry tier at the country's largest branch network. It carries a $15 monthly service fee, waived with a $2,000 minimum daily balance, $2,000 in Chase card purchases, or $2,000 in QuickAccept deposits, and includes $5,000 of in-branch cash deposits per statement cycle at no additional charge.
For a trade that takes cash on the job or deposits paper checks daily, that's the reason to consider it. Built-in invoicing and card acceptance through QuickAccept are included. Third-party fee reviews report domestic wires at $25 outbound, and the account doesn't pay interest on balances.
5. Mercury: A Fit for Contractors Who Rarely Handle Cash
Mercury is a fintech company rather than a bank, with banking services through Choice Financial Group and Column N.A. Core checking and savings carry no monthly fee, domestic USD wires are free, and deposits are eligible for up to $5 million in FDIC coverage through partner sweep networks.
Its IO card pays a flat 1.5% cashback with no personal guarantee, with limits that track cash held on the platform. Mercury has no cash deposit path and doesn't issue checkbooks, so it suits trades that collect by ACH, card, or invoice link and pay subs electronically.
Side-by-Side Comparison
Provider figures reflect publicly published information as of September 2026 and are subject to change.
How to Choose Based on How Your Business Collects and Spends
Work through it in this order.
- Check entity type first: If you're a sole proprietor, Slash isn't yet an option, and forming an LLC or S-Corp is the step that opens the door to the platforms with real spend controls.
- Count your active jobs: Under three at a time, a single card and clean bookkeeping may be enough. Above that, one card per job with its own limit is what keeps a foreman's supply run from landing on the wrong project.
- Look at how customers pay you: Mostly by bank transfer or card, and a platform with invoice links and reminders will shorten your collection cycle. Mostly in cash, and branch or Green Dot deposit access moves up the list.
- Model the materials gap: If you routinely buy $20,000 of materials before a deposit clears, financing terms on the platform matter more than the monthly fee.
- Decide who approves sub payments: If it's not just you, you need approval routing, not a shared login.
Many contractors run two accounts for a reason: a platform for cards, invoicing, and job control, and a traditional account for the cash and checks that still show up. That's a sensible structure, not a compromise.
One Job, Start to Finish, on Slash
Here's how a $48,000 kitchen remodel moves through Slash from signed contract to closed books.
Contract signed. Create a virtual account for the job's customer deposit so it's separated from operating cash. Send the deposit invoice from Slash with an embedded payment link; the homeowner pays by bank transfer and the funds settle into that account.
Materials phase. Issue a virtual card for the job with a $14,000 limit, restricted to your supply houses, and hand it to the foreman. Every purchase shows in the dashboard as it settles. When a receipt is needed, Twin texts the foreman for a photo and matches it to the charge.
Subs on site. The electrician's invoice arrives by email. Forward it to Bill Pay, Slash parses the amount and due date, the project manager approves it, and it pays by RTP on Friday. On Pro, that transfer is $0.
Progress payment. Send the second invoice with a reminder set for three days before due. If the homeowner's payment lands after your next materials order, draw 30-day Working Capital Financing from the dashboard to cover it and repay when the progress payment clears.⁵
Closeout. The job card is frozen, the last invoice is paid, and every transaction, receipt, and sub invoice syncs to QuickBooks Online or Xero already coded to the job. Ask Twin how the project came in against its $14,000 materials budget, and it answers from live data.
Idle cash between jobs can sit in a treasury account with no minimum balance and access to money market funds from Morgan Stanley and BlackRock. A management fee applies to balances below $500,000.⁶
Conclusion
Trade contractors run more simultaneous budgets than most businesses their size, and the bank account is where those budgets either stay separated or blur together. The accounts that serve the trades best are the ones that give each job its own card, its own invoice, and its own approval trail.
Rank on job-level control, invoicing speed, and bill-pay approvals. Then decide whether you also need a branch for cash. Monthly fees come last.
Talk to the Slash team about structuring cards and accounts around your active jobs before the next busy season.
Apply in less than 10 minutes today
Join the 10,000+ businesses already using Slash.
FAQs
1. What is the best business bank account for contractors in 2026?
The best business bank account for contractors in 2026 is Slash for businesses running multiple jobs at once, based on unlimited per-job virtual cards with limits and merchant restrictions, invoicing with embedded payment links and automated reminders, Bill Pay with approval routing, and 30/60/90-day Working Capital Financing. Chase Business Complete Banking suits cash-heavy trades that need branch deposits, and Bluevine suits contractors who want checking yield with a credit line.
The 6 Best Credit Cards for Construction Businesses in 2026

2. Can a contractor give each crew or job its own card?
A contractor can give each crew or job its own card on platforms that issue unlimited virtual cards with per-card controls. Slash issues unlimited virtual cards on both plans, each with a spend limit, per-transaction ceiling, and merchant restriction, and groups them under a crew or division budget.
3. Can sole proprietors open a Slash account?
Sole proprietors cannot currently open a Slash account. Slash business banking is available to US-registered LLCs, C-Corps, and S-Corps, so owner-operators who haven't formed an entity would need to do so first.
4. How do home services businesses get paid faster?
Home services businesses get paid faster by sending invoices with embedded bank-transfer payment links, setting automated reminders ahead of the due date, and using ACH debit authorization for recurring service contracts. Slash invoicing includes all three, and payments settle into a designated virtual account.
5. Are Slash business accounts FDIC insured?
Slash business checking accounts are FDIC insured through partner bank Column N.A., with coverage up to $150 million via Column N.A.'s insured cash sweep network. FDIC insurance protects against the failure of an insured depository institution, not against other losses.
Don't Settle for Less When it Comes to Deposit Insurance
Read more from us


