Slash raises $100M Series C at a $1.4B valuation

Airwallex: A 2026 Review
Figuring out whether Airwallex is right for your business? We've gathered Airwallex’s features, fees, pros and cons, and user reviews all in one place.





Why Businesses Choose Slash
A side-by-side look at Airwallex and Slash:

 Airwallex
- Unlimited virtual cards
- Up to 2% cash back on eligible spend
- Multi-entity financial management
- Working capital lines of credit⁵
- Stablecoin payments with direct on- and off-ramps
- High-yield treasury⁶
- Real-time payment rails for all users
Airwallex is one of the leading financial platforms for businesses that operate across borders. The Airwallex platform offers multi-currency business accounts, corporate cards, and international transfers. But is Airwallex actually the right choice for your business? This assessment breaks down its features, fees, drawbacks, and user feedback.
What is Airwallex?
Airwallex is a financial technology platform largely focused on cross-border payments. It offers multi-currency business accounts with local bank details in currencies including USD, EUR, GBP, HKD, and AUD. The platform also supports transfers to more than 200 countries in over 60 currencies, processes card payments through its own gateway, and provides corporate cards for employee spending. Alongside payment capabilities, Airwallex comes with expense management tools, embedded finance APIs for custom payment flows, and ecommerce integrations with Shopify and WooCommerce. Their accounting integrations include Xero, QuickBooks, Sage Intacct, and NetSuite. It’s important to note that Airwallex is not a bank. In the US, it operates as a licensed money transmitter, works with Evolve Bank & Trust for certain payment services, and issues cards through Community Federal Savings Bank. Customer funds are safeguarded according to the regulations of each market where Airwallex operates, rather than held on Airwallex's own balance sheet.
Who is Airwallex Best For?
Airwallex is a good fit for businesses with high international payment volume, particularly companies that hold balances in several currencies or regularly pay overseas suppliers and contractors. Businesses with entities in multiple regions can benefit from its multi-currency account structure, while ecommerce companies can connect its payment gateway to platforms like Shopify. It is a weaker fit for US businesses that operate primarily domestically. Airwallex's biggest advantages are concentrated in cross-border payments, so companies mainly looking for domestic banking, a rewards-based charge card, treasury products, or stablecoin payments may not be satisfied with what the platform has to offer.
Airwallex Features and Financial Services
Airwallex's core product is their global business account. Companies can hold funds in 20 currencies and receive funds in over 130 currencies. After receiving one of the 130 currencies that isn’t available for holding, you can convert it to your preferred currency right on the Airwallex platform. Their corporate cards are Visa debit cards funded directly from the company's wallet balance, and they carry no international transaction fees. Since the card is a debit card rather than a charge card or credit card, spending is limited to money the business has already deposited. Airwallex natively integrates with quite a few HRIS and accounting apps, including Workday, NetSuite, BambooHR, and Xero. Its embedded finance API allows companies to build custom checkout and payment experiences. The payment gateway supports major card networks, as well as Apple Pay and Google Pay. Expense management features include receipt capture, approval workflows, and the ability to set custom budget limits and category restrictions for individual cards or team members. An automated policy agent can flag or block spending that breaks company rules.
Airwallex Fees and Pricing
Airwallex has three subscription tiers. Explore costs $0 per month in the US and has no minimum balance or deposit requirement. Grow costs $12 per user per month plus a platform fee based on team size. Accelerate, its highest tier, uses a quote-based pricing system. When it comes to foreign exchange, Airwallex charges 0.50% above the interbank rate for eleven major currencies, including USD, HKD, EUR, GBP, and AUD. Other currencies carry a 1.00% margin. Traditional banks often charge somewhere around 1.5% to 3%, meaning Airwallex’s margins can save companies lots of money on conversions over time. Payment acceptance uses a separate fee structure. Domestic card processing costs 2.80% plus a $0.30 gateway fee per transaction. American Express carries additional category surcharges, bringing the rate to 3.10% for restaurants and 3.30% for travel. International card processing costs as much as 4.30%, plus the same $0.30 fee. SWIFT transfers cost $15 when charges are shared or $25 when the sender pays all fees. If you want the option to potentially bypass international wire, Airwallex can connect to local payment rails in more than 120 countries. While these transfers have often been free, that changes on October 12, 2026. From that date, Explore customers will pay between $1 and $7 for international transfers sent over local networks. Grow and Accelerate customers are exempt.
Airwallex Strengths and Limitations
Overall, Airwallex's strongest feature is its international infrastructure. Multi-currency account management is strong, transfer coverage extends to more than 200 countries, local payment rails reach more than 120 countries, and the US Explore plan has no minimum balance requirement. For companies paying contractors or suppliers across several markets, that’s a helpful suite of features. There are tradeoffs, however. Airwallex’s cards are debit cards rather than charge or credit cards, which means spending is limited by the available balance and businesses receive no credit float. Additionally, their advertised “2% cash back” comes with a few asterisks. According to their terms, eligible purchases don’t include in-person transactions, purchases under $100, and anything after the “promotion period” ends on December 31st, 2027. Airwallex also falls short when it comes to its available payment rails. Surprisingly, despite its global positioning, the platform doesn’t support transfers via stablecoin. Additionally, RTP/FedNow is only available for “eligible customers” per Airwallex’s terms.
What Real Users Say About Airwallex
Airwallex's ratings actually vary depending on the review platform and sample size. On Trustpilot, where reviewers don’t have to be verified customers, Airwallex scores roughly 3.3 to 3.5 from about 2,350 reviews. G2, which has a smaller and more curated business audience, rates it 4.2 out of 5 from 53 reviews. Capterra gives Airwallex 3.9 from 15 reviews, including 4.1 for ease of use and 3.4 for customer service. Trustpilot has more than forty times as many reviews as G2 and Capterra combined, meaning its lower rating reflects by far the largest sample rather than being an isolated result. Positive feedback is similar across the three platforms. Customers frequently mention competitive pricing, the convenience of managing multiple currencies in one account, and integrations with accounting and ecommerce platforms. When it comes to negative feedback, you’ll often see mentions of account freezes and payment holds, with some users reporting funds blocked for days or weeks during compliance reviews without a clear explanation. Support reviews are more divided. G2 users often describe responsive support agents, while reviewers on Trustpilot and Capterra more frequently report automated replies and difficulty reaching a human operator. This may indicate that some user issues are prioritized differently by Airwallex behind the scenes.
Why Slash is the Right Airwallex Alternative
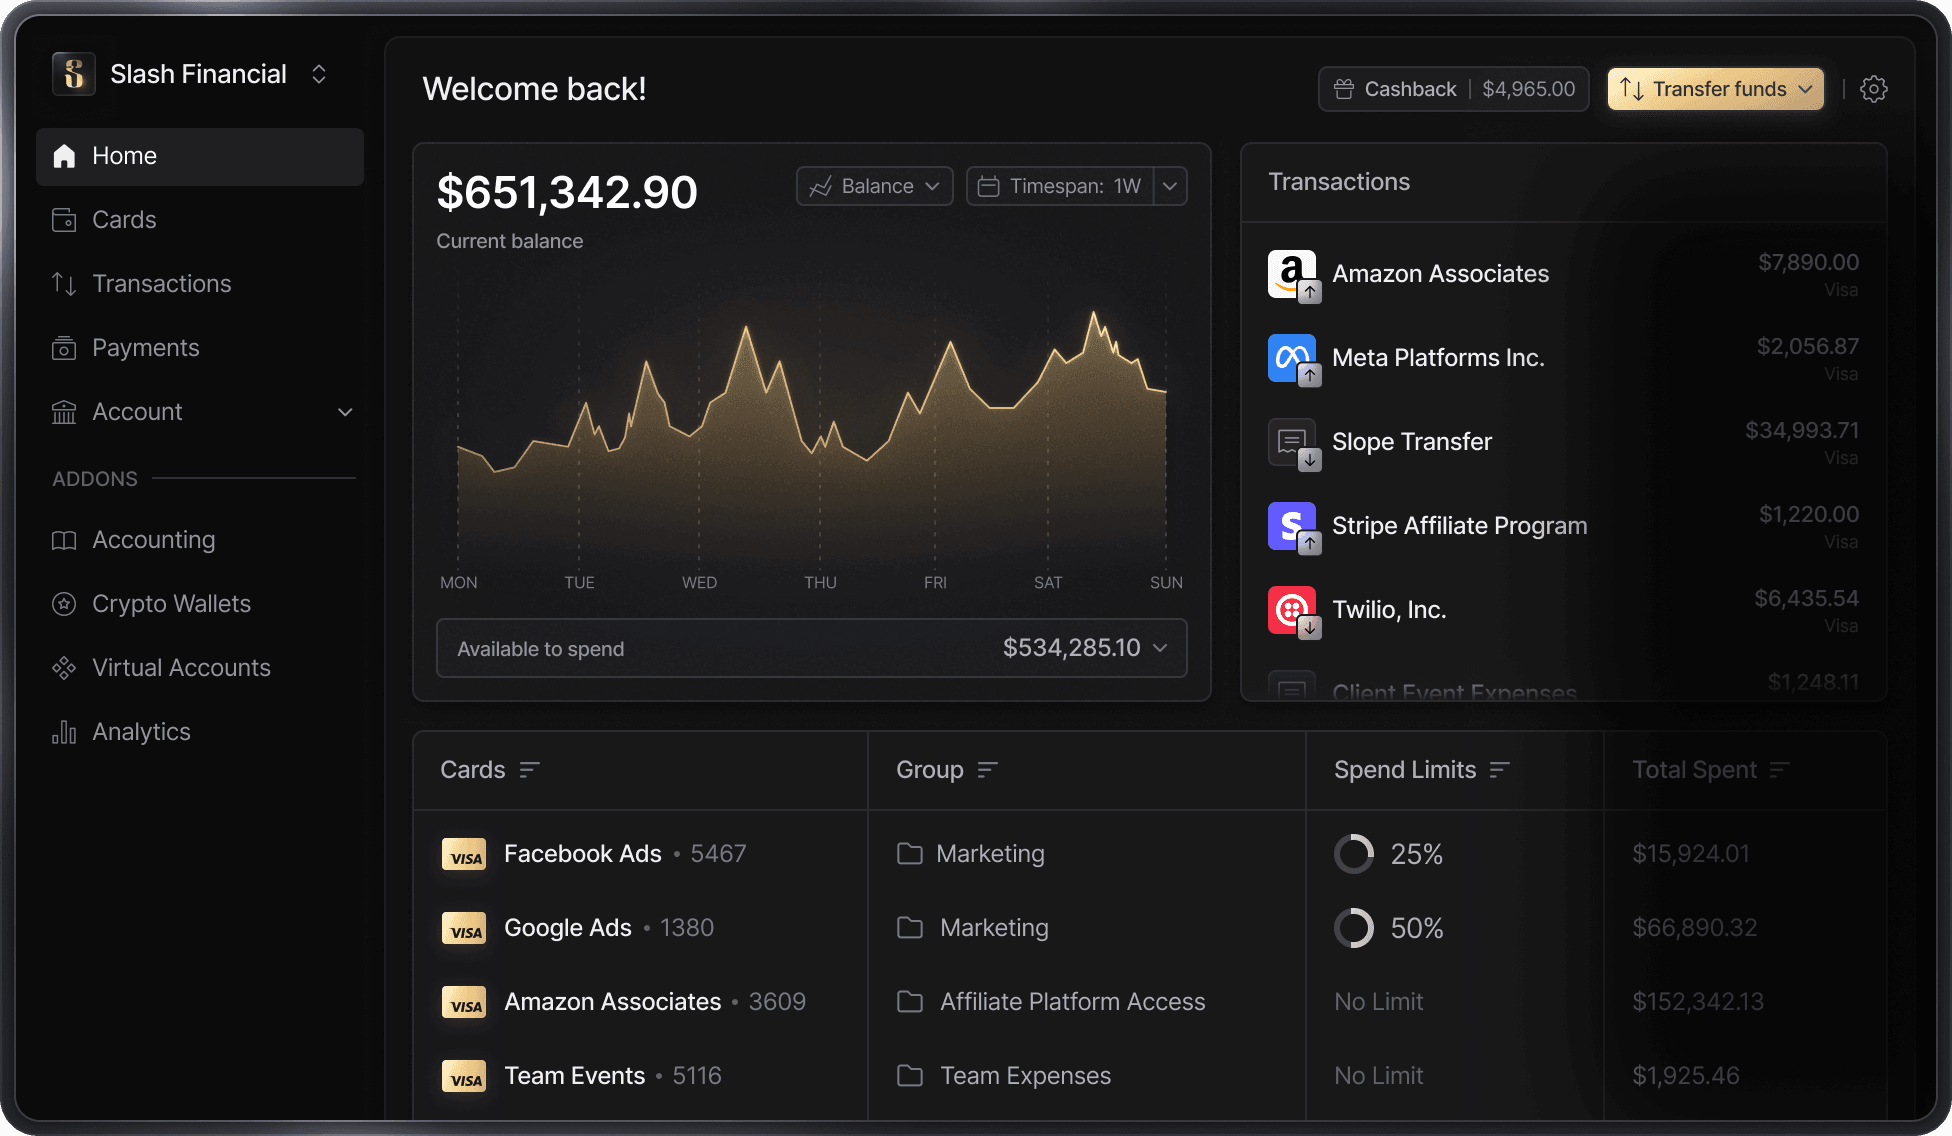
Airwallex is a financial platform that was created for global businesses first. If your company has entities all over the world and you’re looking to use a wide variety of currencies, it can suit your needs rather well. However, if you’re based primarily in the United States, you may notice some of the features Airwallex lacks. For example, Slash offers working capital lines of credit, which gives teams short-term financing with flexible 30-, 60-, or 90-day repayment terms that can help bridge gaps without forcing them into payment cycles that don’t fit their cash flow. Airwallex doesn’t offer working capital lines of credit or loans at all. Their lack of crypto support is also a weak point compared to Slash, which comes with built-in USDC and USDT on/off ramps that can help companies send funds from place to place in minutes. Every Slash customer can use RTP and FedNow to send payments in seconds, provided their recipient also uses the network. Meanwhile, only “eligible customers” get access to Airwallex’s real-time payments. Slash also has Airwallex beat in the realm of high-yield accounts. As of August 2026, Airwallex Yield can earn up to 3.46% annualized yield, while Slash Treasury can earn up to 3.83%. With its international payment rails, Global USD account, and multi-entity management tools, Slash is built to help businesses that operate across borders in the same way Airwallex is. Outside of global features, Slash users get to capitalize on real-time payment networks, working capital lines of credit, an agentic AI assistant, and an overall business banking platform that Airwallex can’t match.¹
Global USD accounts in 130+ countries
Open a dollar-denominated account from anywhere. Hold USD, send wires and ACH, and move stablecoins — all from one dashboard.
Get started with Slash.
Join the 10,000+ business using Slash to elevate how they manage their finances.